

Cash Advance: Get 250 Fast
by KOMPANIIA LORENS PP
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
When an unexpected bill lands between paydays, the hardest part is often not deciding that you need help; it is finding a borrowing process that feels understandable before you commit. I tested Cash Advance: Get 250 Fast as a finance app from KOMPANIIA LORENS PP, focusing less on its short store promise and more on the practical journey from opening the app to deciding whether it belongs in a real emergency plan.
My first impression is that it aims for a narrow job: helping a user explore a payday-loan or cash-advance request without turning the experience into a complicated financial dashboard. It is free to install and intended for Everyone, which makes the entry point approachable. The important distinction, though, is that an easy application screen does not automatically mean an easy repayment decision. I found the app most useful as a way to organize a short-term borrowing request, not as a replacement for savings, budgeting, or a longer-term lending product.
From a sudden expense to a borrowing decision
I start with the expense itself, because a borrowing app is most useful when the need is specific rather than vague. I’d work out the smallest amount that would solve the immediate problem, then consider whether the repayment could fit without pushing another essential bill aside. That gives me a steadier basis for weighing the options that come next.
The starting condition matters more than the download
Imagine a routine weekday going wrong: a necessary repair, a delayed payment, or a household cost arrives before your next paycheck. In that situation, I would not begin by searching for the fastest-looking button. I would first write down the amount actually needed, the date money should arrive, and the date the repayment would have to fit into my budget. That small preparation changes how I use this app because it keeps the request tied to a specific problem rather than an open-ended invitation to borrow.
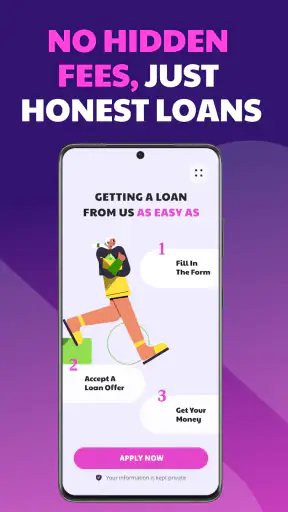
The app’s store summary presents simple steps and no subscription fees, while its short description identifies it as a cash advance service. That positioning is useful, but it should not be confused with free money. A borrowing app can be free to download and still involve costs or repayment obligations connected to an advance. I would therefore treat every displayed condition as something to read carefully, especially the total repayment, timing, eligibility requirements, and consequences of missing a due date.
That is the first non-obvious strength of this particular app: its simplicity can help someone who is already clear about the emergency. The same simplicity can become a weakness for someone who expects a full personal-finance education layer. I did not approach it as a budgeting coach. I approached it as a focused doorway into a short-term cash request.
Opening the app and setting expectations
The app is currently listed as version 1.2.2 and supports Android 7.0 or later. That makes it accessible on many older Android phones, which is practical for users who do not replace devices frequently. At the same time, anyone using an iPhone should not assume that an Android listing automatically represents an iOS experience. I would check the relevant platform before planning around the service, rather than treating the app name alone as proof of availability everywhere.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Its public reception is strong, with a 4.7 average from around 25 thousand ratings and more than 100 thousand installs. Those figures tell me that the basic concept has attracted meaningful use, but they do not answer the questions that matter most to an individual borrower. A high average cannot tell me whether a particular request will be approved, how quickly funds will move, or whether the repayment schedule suits my income. I use the popularity as a reason to investigate the app, not as a reason to skip the investigation.
Before entering personal information, I would also make sure I am using the genuine application associated with KOMPANIIA LORENS PP. In finance, this handoff between a store page and an installed app deserves more attention than it receives in ordinary utility apps. I would check the developer name, review the screens carefully, and avoid entering sensitive details into anything that arrived through an unexpected message or unfamiliar download source.
The step-by-step flow is short, but the reading is important
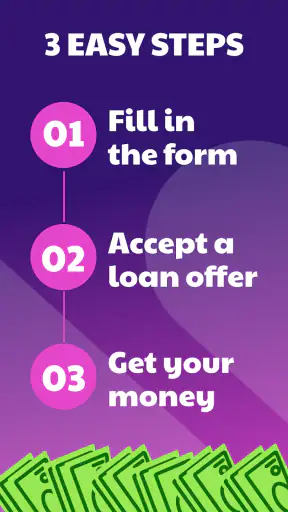
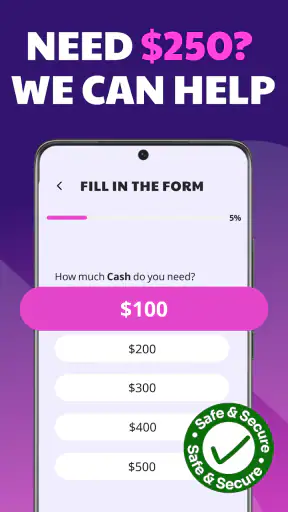
Once I have a defined amount in mind, the logical flow is straightforward: open the service, follow the cash-advance application steps, provide the requested information, review the resulting terms, and decide whether to continue. The attractive part is the reduced cognitive load. I am not navigating investment charts, credit-building lessons, or a collection of unrelated financial tools. The app stays close to the immediate borrowing task.
That narrow flow also creates a useful habit: pause at every screen that changes the financial commitment. I would not rush through identity, income, bank, or repayment details merely because the interface feels quick. A fast form is only helpful when the information entered is accurate. An incorrect account detail or misunderstood repayment date can create more stress than the original emergency, so I would keep the relevant documents and calendar available while completing the request.
One practical technique I found valuable is to separate “application information” from “approval information” in my own notes. The first describes what I submit. The second describes what the lender may offer after review. They are not the same thing. The amount I hope to receive, including the advertised reference to 250, should never be treated as a guaranteed outcome. I would wait for the actual offer and read its conditions before making plans around the money.
The most important screen is the one that turns a request into a repayment obligation. I would look for the amount received, the total amount repaid, the schedule, any applicable fees, and what happens if repayment is late. If those details are not clear enough to explain aloud to another person, I would stop rather than proceed. This is not unnecessary caution; it is the difference between using a cash advance deliberately and accepting a commitment under pressure.
Handoffs: where the app meets the real financial system
The app is only one part of the journey. After I enter information, the request may need to pass through eligibility checks, identity verification, a lending decision, and a money-transfer process. Those handoffs are where expectations often become unrealistic. The app can present a clean interface, but it cannot make every outside step instantaneous or guarantee that the result will match the initial request.
I would therefore keep the original bill’s deadline separate from the application’s progress. If a payment is due today, I would not assume that starting a request means the funds are already available. I would contact the biller, ask about an extension, or consider a safer backup plan while waiting for a decision. This is one of the most useful ways to use the app responsibly: treat an application as an attempt, not as money in hand.
Another handoff involves the user’s own bank account and regular income. A cash advance only solves the immediate problem if the later repayment fits the next budget. I would map the repayment against rent, food, transport, utilities, and existing debt before accepting anything. If the advance would force me to borrow again for ordinary essentials, the app is no longer solving a temporary gap; it is helping postpone a larger shortfall.
This is also where the app differs from a traditional bank loan. A bank or credit union may take longer and ask for more documentation, but it may offer clearer long-term structures or a relationship with an adviser. A credit card can be more flexible for a purchase, though interest and fees can still make it expensive. An employer-based earned-wage service may be better suited when the need is limited to wages already earned. A local assistance program or payment arrangement may be slower to find but cheaper than borrowing.
Compared with those alternatives, Cash Advance: Get 250 Fast is appealing when the user values a focused digital route and needs to explore a short-term option without a subscription fee. It is less attractive when the user needs a larger, longer repayment period, personal guidance, debt restructuring, or help understanding a damaged credit profile. The right comparison is not “which app is fastest?” but “which option creates the least harmful total outcome for this particular gap?”
A realistic everyday workflow
Suppose I have a necessary household expense before payday and decide to investigate a cash advance. I would begin by calculating the exact shortfall instead of entering the maximum amount automatically. Then I would open the app, move through the request screens slowly, and keep a note of every figure that affects repayment. If an offer appears, I would compare the amount that reaches me with the total amount leaving my account later.
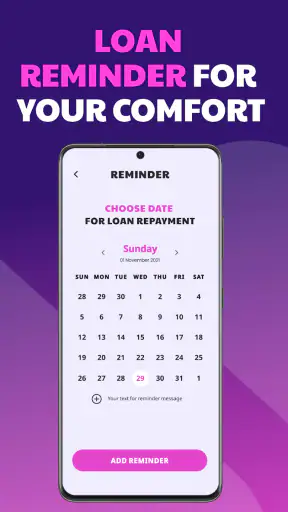
Next comes the handoff to my calendar. I would record the repayment date and set a reminder several days beforehand, leaving room for a transfer problem or a change in my pay schedule. I would also remove the borrowed amount from my next discretionary spending plan immediately. That sounds obvious, but it prevents the common mistake of mentally treating the advance as extra income.
If the terms fit, the app has served a clear purpose: it has helped me examine a short-term option in one place. If the terms do not fit, cancelling the process is a successful outcome, not a failure. The ability to say no after seeing the real obligation is more valuable than forcing an approval simply because the original expense felt urgent.
A second useful scenario is a user with irregular income. For that person, a fixed repayment date can be harder to manage than the application itself. I would not rely on an expected freelance payment or uncertain shift schedule unless the money was genuinely dependable. In this case, a slower option with more predictable installments may be safer, even if the cash-advance route looks more convenient at the beginning.
What the result can and cannot tell you
The result of the workflow is not simply approved or declined. A useful result is a clear answer to four practical questions: how much money would arrive, how much would need to be repaid, when repayment would occur, and whether that date works with the rest of the month. The app is worthwhile when it helps me reach those answers without hiding the decision behind unnecessary distractions.
I also appreciate that the service is presented without a subscription fee. That makes it different from finance tools that charge for ongoing access to basic features. Still, “no subscription” does not settle the affordability question. A one-time borrowing cost, transfer condition, or late consequence can matter far more than a recurring app charge. I would judge the offer by its complete repayment picture, not by the absence of a membership payment.
The app’s age rating of Everyone makes the product broadly presented, but borrowing is not an everyday decision for every person. A young user, someone without dependable income, or anyone already behind on several obligations should involve a trusted adult or financial adviser before accepting a short-term advance. The rating describes access to the app, not suitability for every financial situation.
For a user who wants a simple starting point, the current version feels appropriately focused. For an experienced borrower who wants detailed repayment simulations, long-term debt tools, or a complete account-management platform, the experience may feel too limited. I would not criticize it for lacking features outside its central purpose, but I would be direct about the trade-off: the app’s value comes from concentration, not breadth.
Where the flow breaks down
The biggest friction is the tension between an urgent need and the time required to make a responsible decision. When money is tight, users may skim terms and assume the most favorable interpretation. The app cannot remove that human pressure. I would use it only when I have enough time to read the offer, verify the repayment date, and consider an alternative if the conditions are unsuitable.
Another breaking point is uncertainty around eligibility or timing. A polished application process may encourage optimism before a final result exists. I would avoid scheduling a payment around funds that have not arrived. If the request is not accepted, or if the amount differs from what I expected, the backup plan needs to exist independently of the app.
The flow also breaks when the requested amount is used to cover a recurring deficit. A single emergency and a monthly pattern are very different problems. If I needed advances repeatedly for groceries, housing, or transportation, I would stop using short-term borrowing and seek a budget review, creditor arrangement, community support, or a lower-cost lending solution. Repeating the same emergency workflow does not fix the underlying cash-flow gap.
Finally, the app is not the right choice for anyone who cannot identify a realistic repayment source. That includes people whose next paycheck is already committed, users facing unstable employment, and borrowers considering one advance to repay another. In those cases, the convenience of a digital application is outweighed by the risk of creating a cycle that becomes harder to escape.
My recommendation after following the complete journey
I see Cash Advance: Get 250 Fast as a focused finance app for investigating a small, short-term cash need. Its free entry, simple presentation, broad Android compatibility, and strong user response make it easy to consider. The developer, KOMPANIIA LORENS PP, has kept the product centered on the cash-advance task rather than surrounding it with a large collection of unrelated tools.
My recommendation comes with a firm condition: use it as a comparison and decision tool, not as permission to borrow automatically. Prepare the exact amount, read the complete offer, confirm the repayment schedule, and keep a backup plan for the original bill. If the total obligation fits comfortably after essential expenses, the app may be a practical route to explore. If it does not, a lender with longer terms, a bank or credit union, an earned-wage option, a payment arrangement, or non-borrowing assistance may be the better answer.
In the end, the app’s best feature is the focused path from a cash problem to a concrete offer. Its main weakness is the same focus: it does not replace the broader judgment needed to decide whether borrowing is wise. I would recommend it to a careful user facing a genuine one-off gap, while advising anyone with recurring shortages or uncertain income to pause and look for a solution that addresses the cause rather than only delaying the pressure.
Pros
- Fast application process with minimal paperwork required
- Clear repayment terms are shown before accepting an offer
- May help cover unexpected expenses between paychecks
- Available online without needing to visit a physical branch
- Useful eligibility information is provided during the application
Cons
- Approval and loan availability may depend on your location
- Fees and interest can make short-term borrowing expensive
- Repayment deadlines may be difficult for some users to meet
- Personal and financial information is required to apply
- Not suitable as a long-term solution for recurring money problems
FAQs for Cash Advance: Get 250 Fast
What is Cash Advance: Get 250 Fast, and how does it work?
Cash Advance: Get 250 Fast is a financial app designed to help users explore short-term cash advance options through a mobile application. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can evaluate your request. The app may connect you with third-party lenders or financial providers, so approval, loan amounts, fees, and repayment terms can vary.
Can everyone receive a $250 cash advance through the app?
No. The advertised amount should not be understood as a guaranteed payment for every user. Eligibility depends on factors such as your location, age, income, employment details, banking history, and the requirements of participating providers. Even if you complete the application successfully, a lender may decline the request or offer a different amount, interest rate, fee structure, or repayment schedule.
Are there fees, interest, or other costs associated with using Cash Advance: Get 250 Fast?
Potentially, yes. Depending on the provider and the product offered, you may encounter subscription charges, service fees, origination fees, expedited-transfer fees, interest, or other costs. Carefully review the final offer and all disclosures before accepting anything. The app itself may not be the lender, and the actual cost is generally determined by the third-party provider presenting the advance.
What information does the app require, and is it safe to provide my details?
A cash advance application may request sensitive information, including your name, contact details, identification data, employment and income information, bank account details, and permission to verify financial records. Before submitting anything, read the app’s privacy policy, check how data is shared, and confirm that you are using the official listing. Never provide passwords, verification codes, or banking credentials through suspicious messages or unofficial websites.
When will I receive the money, and how is repayment handled?
Funding speed is not guaranteed and can depend on approval time, bank processing, verification checks, weekends, and the delivery method selected. Some offers may provide same-day or expedited access, while standard transfers can take longer. Repayment terms also vary by provider and may involve an automatic debit from your bank account. Review the due date, total repayment amount, extension rules, and consequences of late payment before accepting an offer.











